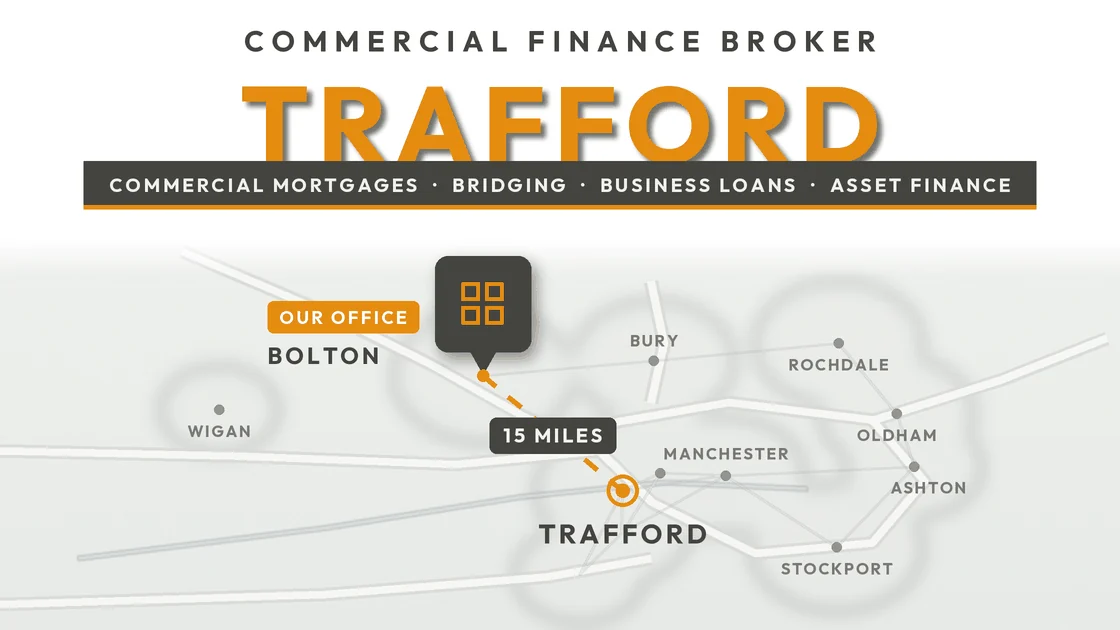
Bolton Business Finance is an independent commercial finance broker working with businesses and property investors across Trafford and Altrincham. We arrange limited company buy to let and property investment finance, commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance and merchant cash advances. Trafford Park is about twelve miles from our office and Altrincham about seventeen.
We arrange buy to let and commercial mortgages in Trafford for limited company landlords, portfolio investors and businesses buying their own premises. We do not lend ourselves. We approach the lenders most likely to say yes to your particular case. Trafford is the most expensive borough in the North West and its rental yields are the thinnest we deal with anywhere, which changes how a purchase here needs to be structured.
Written by Marcus Wright, owner and founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed September 2026.
Looking for a mortgage broker in Altrincham for a home to live in? We are not the right firm. Bolton Business Finance is not FCA authorised and arranges business finance only. We cannot advise on residential mortgages or consumer buy to let. Use the FCA’s Financial Services Register to find an authorised adviser. If you are funding property through a limited company or running a business, read on, you are in the right place. There is more detail further down this page.
On this page
- We will come to you in Trafford and Altrincham
- Buy to let and property investment in Trafford
- Why prices and rents have pulled apart here
- Commercial mortgage broker Trafford
- Trafford Park and Altrincham, two different funding jobs
- Bridging and development finance
- Business loans and asset finance
- What we do not do
- Meeting us in Trafford and Altrincham
- Trafford and Altrincham commercial finance FAQs
- Apply for commercial finance in Trafford
The short version
- A commercial finance broker arranges funding for businesses from lenders across the market, rather than lending money itself.
- We are not FCA authorised. No residential mortgages and no consumer buy to let, which matters here because a lot of Altrincham searches are for exactly that.
- Trafford had the highest average house price in the North West in June 2026, at £397,000.
- Prices rose 9.7% over the year while rents rose 2.5%, so the yield has fallen from about 4.4% to about 4.1%. It is the thinnest yield of anywhere we cover.
- On an average priced property the rent supports a loan of roughly 60% of value, not the 75% most investors plan around.
We Will Come To You In Trafford and Altrincham
Trafford spreads a fair distance. Trafford Park, Stretford and Urmston are about twelve or thirteen miles from Westgate House, usually twenty five minutes down the M61 and M60. Sale and Timperley are a little further. Altrincham, Bowdon and Hale sit at the southern end at roughly seventeen miles and closer to thirty five minutes.
| Item | Detail |
|---|---|
| Areas covered | Trafford Park, Old Trafford, Stretford, Urmston, Flixton, Davyhulme, Sale, Ashton upon Mersey, Timperley, Altrincham, Bowdon, Hale, Hale Barns, Dunham Massey, Partington and Carrington |
| Distance from our office | Twelve or thirteen miles to Trafford Park and Urmston, about seventeen to Altrincham and Hale |
| Products arranged | Limited company buy to let, commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance, merchant cash advances |
| Lender panel | Over 135 lenders, from high street banks to specialist and non-bank funders |
| Broker fee | None on most facilities, we are paid a disclosed commission by the lender. Property secured deals carry £495 upfront and 1% on completion |
| First meeting | Free, at your premises, your accountant’s office or ours |
| Regulatory status | Not FCA authorised. Non-regulated business finance only. No residential mortgages and no consumer buy to let |
Buy To Let and Property Investment in Trafford

According to ONS and HM Land Registry data, the average house price in Trafford was £397,000 in June 2026, up 9.7% on the year from £362,000. ONS notes that this gave Trafford the highest average house price in the North West, where the regional average was £220,000. Average private rent was £1,367 a month in July 2026, up 2.5% from £1,334.
Those two numbers are the whole story of Trafford as an investment proposition, and they are pulling in opposite directions.
| Property type | Average price, June 2026 | Average rent, July 2026 | Gross yield |
|---|---|---|---|
| Flats and maisonettes | £218,000 | £1,119 | 6.2% |
| Terraced | £347,000 | £1,355 | 4.7% |
| Semi-detached | £449,000 | £1,519 | 4.1% |
| Detached | £800,000 | £2,040 | 3.1% |
A detached house in Trafford averages £800,000 and rents for £2,040, which is 3.1% gross. At that level the rent will not come close to satisfying a lender’s rental cover test at any normal loan to value, so a detached purchase here is effectively a cash or very low leverage proposition rather than a geared one. That is not a criticism of the asset. It is simply what the numbers do, and it is better understood before you instruct anyone.
Business purpose only
We arrange buy to let and property investment finance on a business basis only, through limited companies, partnerships and portfolio landlords. We are not FCA authorised and we do not arrange consumer buy to let, regulated buy to let or any residential mortgage. If the property is or will be lived in by you or a close family member, that is regulated business and you need an FCA authorised mortgage adviser instead.
Why Prices and Rents Have Pulled Apart in Trafford
Over the year to mid 2026, Trafford house prices rose 9.7% and Trafford rents rose 2.5%. That is close to a fourfold difference, and it happened in a single twelve month period.
| Measure | Mid 2025 | Mid 2026 | Change |
|---|---|---|---|
| Average house price | £362,000 | £397,000 | Up 9.7% |
| Average monthly rent | £1,334 | £1,367 | Up 2.5% |
| Gross yield | About 4.4% | About 4.1% | Compressing |
For an owner who already holds Trafford property, that is a good year. The asset is worth more and the rent has not fallen. For a buyer, it is the opposite: you are being asked to pay nearly ten per cent more for an income stream that has grown by two and a half. Every pound of purchase price now buys less borrowing capacity than it did a year ago.
That second point is the one that produces declined applications. Buy to let lending is sized by whether the rent covers the mortgage interest by a set margin at a stress rate, commonly 125% cover for a limited company borrower. It is not sized by your income or by the deposit you have available. So when the rent stops keeping pace with the price, the maximum loan falls as a proportion of the purchase, regardless of how strong you are as a borrower.
What that means in pounds
On an average priced Trafford property at £397,000, with rent at £1,367 a month, 125% interest cover and a 5.5% stress rate, the rent supports a loan of roughly £239,000. That is about 60% of value, not 75%. In deposit terms it is around £158,000 rather than £99,250, so roughly £58,750 more cash than a straight 25% deposit calculation would suggest.
Cover ratios and stress rates vary by lender, by product and by the length of the fixed period, and some lenders apply a floor rate regardless of the rate you pay. Treat this as an illustration of the mechanism rather than a quote. The mechanism itself does not vary, and in Trafford it is what limits the loan.
There is a practical consequence. Lenders generally stress five year fixed products more gently than two year ones, because the borrower is protected from rate movement for longer. In a low yield area that is often the difference between a case working and not working, so Trafford investors frequently end up on a five year fix for reasons of loan size rather than rate preference. If your plan depends on refinancing in two years, say so at the outset, because it narrows the field considerably here.
One honest caveat on the 9.7%
A near ten per cent annual rise in a single borough is a large movement, and ONS states on the same release that local housing data is based on a smaller number of properties than national estimates, which makes short term trends more variable. The figures are also provisional and get revised. The direction of travel in Trafford is clear enough and consistent with it being the most expensive borough in the region, but we would not build a five year plan on one year’s number, and neither should you.
Commercial Mortgage Broker Trafford
A commercial mortgage is a loan secured against property used for business purposes. That covers premises your own business trades from, and property you buy to let to a commercial tenant. Terms usually run 3 to 25 years, occasionally up to 30. Lenders typically advance up to 70% of value on commercial property and up to 75% on semi-commercial, meaning a shop or office with a flat above it.
What decides your terms
- Property type. Standard industrial, warehousing and offices attract the widest choice. Pubs, hotels, care homes and petrol stations attract specialists only.
- Whether you occupy it or let it. Owner occupied is assessed on your trading accounts. Investment is assessed on the rent and the strength of the tenant.
- Unit size. Large industrial units carry their own issue, covered below.
- Lease length. A short unexpired lease on an investment property narrows the field quickly.
- Trading history. Two years of filed accounts opens most doors. Less than that pushes you toward specialists.
- Condition and EPC. Commercial property let in England generally needs an EPC of E or better.
Be realistic on timing. In our experience a commercial mortgage takes 3 to 6 months from first enquiry to completion, and longer on a complicated case. Valuation and legal work are the two stages that overrun most often. If your deadline is weeks rather than months, bridging is usually the honest answer and we will say so.
Our main commercial mortgage broker page sets out lender appetite and typical loan to value by property type, from industrial and offices through to pubs, care homes, petrol stations and places of worship.
Trafford Park and Altrincham, Two Different Funding Jobs
Trafford contains two business economies that have very little to do with each other, and the enquiries that come from each end of the borough look nothing alike.
Trafford Park and the industrial north
Trafford Park is one of the oldest and largest planned industrial estates in Europe, and the businesses on it are manufacturers, distributors, logistics operators and their suppliers. The funding needs are capital equipment, fleet, premises and the working capital gap that comes from selling to large customers on long payment terms.
- Asset finance for plant, machinery, forklifts, racking and commercial vehicles, with nil deposit options and no broker fee
- Invoice finance, which is the standard answer when your customers are large and their terms are sixty or ninety days
- Owner occupier commercial mortgages where a business wants to buy the unit it has been renting
Large industrial units narrow the lender pool
It is worth knowing early that big sheds are not simply small sheds with a bigger number attached. As unit size and value rise, the number of lenders willing to take the asset falls, because a large single-let industrial building is harder to re-let and harder to sell if things go wrong. Lenders think about who else would take the space, and in a specialised or very large unit that list is short. Expect more questions about the covenant of the occupier, the flexibility of the building and the alternative uses for it than you would face on a standard trade unit.
Altrincham, Hale and the southern town centres
The southern end of the borough is a professional services and independent retail economy. Altrincham town centre has had a genuine revival around its market and the independent food and drink trade that grew up with it, and Hale and Bowdon carry high value commercial and mixed use stock along their main streets.
- Professional practices, solicitors, accountants, surveyors and consultancies, needing working capital, office purchase or partner buy-in funding
- Independent hospitality and retail, where fit-out finance and merchant cash advances repaid from card takings are the usual routes
- Mixed use investment, shops and offices with flats above, which is semi-commercial and sits at up to 75% loan to value
- Healthcare and clinic premises, dental and cosmetic practices in particular, which are specialist lending in their own right
The recurring problem at this end of the borough is the ground floor commercial unit underneath residential flats. It looks like a simple semi-commercial case and frequently is not, because the lease structure, the service charge apportionment and the question of who actually controls the building all need resolving before a lender will commit. If you are buying one, get the lease in front of us early.
Bridging and Development Finance in Trafford
Bridging is short term property lending, usually three to eighteen months, priced monthly and repaid from a sale or a refinance.
- Buying at auction, where completion is fixed at twenty eight days
- Buying a property no mainstream lender will touch, typically no kitchen, no bathroom or serious damp
- Refurbishing before refinancing onto a term buy to let facility
- Breaking a chain when a sale slips
- Raising working capital quickly against property already owned
Two numbers that catch people out here
The 180 day value. Bridging lenders size the loan against what the property would fetch in a forced six month sale, routinely 10% to 20% below the open market valuation you paid for. On Trafford values that percentage is a very large absolute sum, so run your figures off the cautious number from the start.
The exit. Bridging is repaid from a sale or a refinance, and if your exit is a refinance onto a buy to let facility, that facility faces the rental cover test set out above. In Trafford that test is tight. A bridge with a refinance exit the rent will not actually support is a bridge without an exit. Work the term loan out first and the bridge second.
Development finance funds building work rather than a purchase, released in stages against a schedule of works with a valuer signing off each drawdown.
- Land or acquisition drawdown. Usually up to 60% to 70% of the purchase price, released on completion.
- Staged build drawdowns. Released in arrears against work completed and signed off by the lender’s monitoring surveyor.
- Practical completion. Final drawdown, and the point at which the exit route has to be real rather than intended.
- Exit. Sale of the units, or refinance onto a commercial mortgage or buy to let facility.
Business Loans and Asset Finance in Trafford
Across the UK, 99.18% of businesses employ fewer than 50 people and around three quarters employ nobody beyond the owners, according to the government’s Business Population Estimates for 2025. Trafford has some very large employers in it, but the businesses that call us are overwhelmingly at that smaller end.
- Unsecured business loans, typically £10,000 to £500,000, decisions in days rather than weeks
- Asset finance, for vehicles, plant, machinery and equipment, with nil deposit options and no broker fee
- Invoice finance, releasing cash tied up in unpaid invoices, which is the usual answer for anyone supplying large customers on long terms
- Secured business loans, larger sums against property, slower but cheaper
- Merchant cash advances, repaid as a percentage of card takings, which suits Altrincham and Hale hospitality and retail
If you have already been declined
A decline tells you about that lender’s criteria rather than about whether your business can be funded. Lenders refuse cases for reasons that have nothing to do with the strength of the business: sales below their minimum, a director who does not own a home, a payment provider their systems cannot read, an application already sitting with another introducer. We have placed cases that had been turned down repeatedly, with nothing about the business having changed. What changed was which lender was looking at it.
What We Do Not Do
We do not arrange residential mortgages, and we do not arrange consumer buy to let. This matters more on this page than on most of our area pages, because a lot of people searching for a mortgage broker or mortgage adviser in Altrincham are looking for help buying a home. We are not that firm and we cannot help with it.
Business buy to let, held through a limited company or as part of a genuine property investment business, is not regulated and we can arrange it. Consumer buy to let, broadly where you did not set out to be a landlord, or where the property has been or will be lived in by you or a close family member, is regulated and we cannot.
Bolton Business Finance Ltd is not authorised or regulated by the Financial Conduct Authority. We arrange non-regulated commercial and business finance only. That means we cannot advise on or arrange: residential mortgages, first time buyer mortgages, remortgages of your own home, consumer buy to let, equity release, or any consumer credit.
If you need any of those, use the FCA’s Financial Services Register to find an authorised adviser. It is free to search and it will tell you whether a firm is genuinely authorised for the business you need. If you are a business owner, a landlord holding property through a company, or a property investor funding on a commercial basis, then you are in the right place and the rest of this page applies to you.
Meeting Us in Trafford and Altrincham
We do not have an office in Trafford or Altrincham and we are not going to pretend otherwise. We are based at Westgate House in Bolton, between twelve and seventeen miles away depending on which end of the borough you are at, and we travel across Trafford regularly.
Where we will meet you
- At your premises, anywhere from Trafford Park and Stretford through to Sale, Timperley, Altrincham and Hale.
- At the property, which on an industrial unit or a mixed use building is worth doing, because the configuration drives the lender shortlist.
- At your accountant’s office, which often saves a meeting later when the figures come up.
- At ours in Bolton, if you would rather come to us. Free parking.
Trafford and Altrincham Commercial Finance FAQs
Do you actually visit clients in Trafford and Altrincham?
Yes. Trafford Park, Stretford and Urmston are about twelve or thirteen miles from our Bolton office, roughly twenty five minutes on the M61 and M60. Altrincham, Bowdon and Hale are about seventeen miles and closer to thirty five minutes. We cover Trafford Park, Old Trafford, Stretford, Urmston, Flixton, Davyhulme, Sale, Ashton upon Mersey, Timperley, Altrincham, Bowdon, Hale, Hale Barns, Dunham Massey, Partington and Carrington. We meet clients at their premises, at the property, or at their accountant’s office. There is no charge for a first meeting and no obligation to proceed. If you would rather come to us, we are at Westgate House, Westgate Avenue, Bolton, BL1 4RF.
Can you arrange a mortgage for a house in Altrincham?
No. Bolton Business Finance is not authorised or regulated by the Financial Conduct Authority and we arrange non-regulated business finance only. We cannot advise on or arrange a residential mortgage, a first time buyer mortgage, a remortgage of your own home, consumer buy to let or equity release. If that is what you need, use the FCA’s Financial Services Register to find an authorised adviser. What we can do is arrange property finance on a business basis, which means limited company buy to let, portfolio landlord lending, commercial mortgages, bridging and development finance. If you are buying an investment property through a company rather than a home to live in, that is our work.
Why can I not borrow 75% on a Trafford buy to let?
Because the rent runs out before the loan to value cap does. Buy to let lending is sized by whether the rent covers the mortgage interest by a set margin at a stress rate, commonly 125% cover for a limited company borrower, rather than by your income or your deposit. Trafford has the highest average house price in the North West but rents rose only 2.5% last year against a 9.7% rise in prices, so the gross yield has fallen to about 4.1%, the thinnest of anywhere we cover. On an average priced property at 125% cover and a 5.5% stress rate, the rent supports a loan of roughly £239,000 against a £397,000 value, which is about 60% rather than 75%. Cover ratios and stress rates vary by lender and product, so treat that as an illustration of the mechanism rather than a quote. One practical point: five year fixed products are generally stressed more gently than two year ones, so in a low yield area the length of the fix often decides the loan size, not just the rate.
How long does a commercial mortgage take?
Typically 3 to 6 months from first enquiry to completion, and longer on a complicated case. Valuation and legal work are the two stages that overrun most often. If your deadline is weeks rather than months, bridging is usually the honest answer and we will tell you that rather than start an application that cannot land in time.
How much can I borrow?
On commercial property, typically up to 70% of value, or up to 75% on semi-commercial. On limited company buy to let it is driven by the rental income against the stressed payment rather than by your own income, and in Trafford that test is usually what limits the loan. On unsecured business loans, commonly £10,000 to £500,000 depending on turnover and trading history. On asset finance it is driven by the asset itself, with nil deposit options available.
Can you help if I have already been declined?
Often, yes. A decline reflects one lender’s criteria, not a verdict on your business. Lenders turn cases down for reasons that have nothing to do with whether the business is sound, and with more than 135 lenders on our panel the question is usually which one to approach rather than whether anyone will look at it. Tell us who has already seen the case, because approaching the same lender twice through a different route does not help you.
Do you charge a broker fee?
Not on most facilities. On business loans, asset finance, invoice finance and merchant cash advances we are paid a commission by the lender, which is disclosed to you. Property secured deals carry a £495 upfront fee and 1% on completion. You will know the full cost before anything is submitted.
Apply For Commercial Finance in Trafford
Tell us what you need funding for
Send us the outline and we will tell you honestly whether it is fundable, roughly what it should cost, and how long it will take. On a Trafford buy to let, send the asking price and the expected rent and we will tell you what the rent actually supports before you offer. No charge for the conversation and no obligation to proceed. Call 0161 546 9128 or use the form below.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd. He has worked in financial services since 2008, beginning at Santander, and has been a commercial finance broker since March 2019. He founded the firm in 2020 and is a member of the National Association of Commercial Finance Brokers.
He arranges commercial mortgages, bridging finance, development finance, business loans, asset finance, invoice finance and merchant cash advances for UK businesses, working with a panel of more than 135 lenders. He can be reached on 0161 546 9128.
Bolton Business Finance Ltd is registered in England and Wales, company number 12495909. Registered office: Westgate House, Westgate Avenue, Bolton, BL1 4RF.
Bolton Business Finance Ltd is not authorised or regulated by the Financial Conduct Authority. We arrange non-regulated commercial and business finance only, and do not advise on or arrange residential mortgages, consumer buy to let, equity release or consumer credit. All finance is subject to status, lender criteria and credit assessment. Your property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.