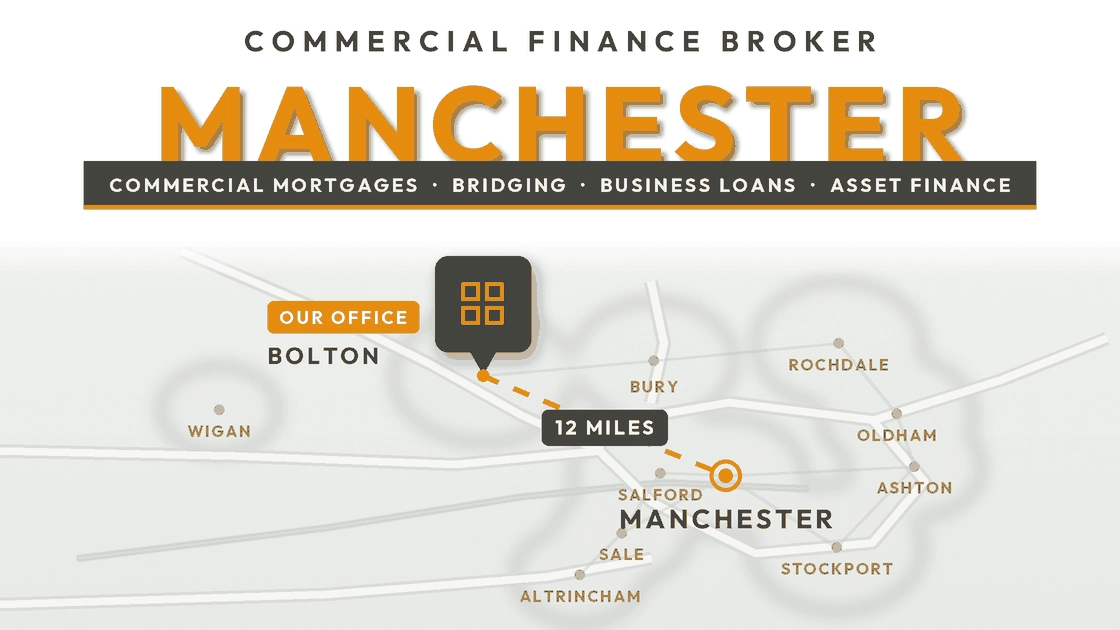
Bolton Business Finance is an independent commercial finance broker serving Manchester and the wider North West. We arrange commercial mortgages, bridging, development finance, business loans, asset finance and invoice finance for businesses and property investors. Our office is twenty five minutes from the city centre, straight up the M61.
We are the commercial mortgage broker Manchester businesses can actually sit down with. We do not lend ourselves. We approach the lenders most likely to say yes to your particular case, and we will come to your premises rather than handle the whole thing by email.
Written by Marcus Wright, owner and founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed September 2026.
On this page
- We will come to you in Manchester
- Commercial mortgage broker Manchester
- Bridging finance in Manchester
- Business loans and asset finance
- Buy to let and property investment
- Development finance
- Manchester businesses we work with
- Meeting us in Manchester
- Manchester commercial finance FAQs
- Apply for commercial finance
The short version
- A commercial finance broker arranges funding for businesses from lenders across the market, rather than lending money itself.
- A commercial mortgage is a loan secured against property used for business purposes, either premises your own business trades from or a property you let to a tenant.
- UK lenders typically advance up to 70% of value on commercial property and up to 75% on semi-commercial, over terms of 3 to 25 years.
- More than 100 lenders are active in the UK commercial mortgage market. A decline from one tells you about that lender’s criteria rather than about your business.
- A commercial mortgage in Manchester usually takes 3 to 6 months from enquiry to completion. Bridging completes in days to a fortnight where the deadline is tighter.
We Will Come To You In Manchester
Manchester is a short drive from our Bolton office, so meeting face to face at your premises is straightforward and costs you nothing. If you would rather come to us, we are at Westgate House on Westgate Avenue, just off the A666, with parking on site.
Most brokers now handle everything by email. On a commercial mortgage or a development case, sitting down with the numbers in front of you usually saves a fortnight of back and forth, and it is the reason we keep doing it.
| Item | Detail |
|---|---|
| Areas covered | Manchester city centre, Ancoats, the Northern Quarter, Salford Quays, Trafford, Wythenshawe, Didsbury, Chorlton and the wider Greater Manchester area |
| Distance from our office | About 12 miles. Roughly 25 to 30 minutes off peak and 45 minutes to an hour in rush hour, via the M61 and M60 or the A666 |
| Face to face appointments | Yes, at your premises or at our Bolton office. Free and without obligation |
| Products arranged | Commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance, merchant cash advance |
| Lenders | More than 100 active in the UK commercial market, with 135+ on our panel |
| Broker fee | None on most facilities. Property secured deals carry £495 upfront and 1% on completion |
| Regulated status | Not authorised by the Financial Conduct Authority. Non-regulated, business purpose lending only |
Commercial Mortgage Broker Manchester
A commercial mortgage is a loan secured against property used for business purposes, either premises your own business trades from or a commercial property you let to a tenant. It is the single most common thing we are asked for in Manchester, and the one where the choice of lender makes the biggest difference to what you end up paying.
Manchester commercial property splits into two very different markets, and lenders treat them very differently. City centre offices are as tight as they have been in years, with prime rents reaching £45 per square foot at No.1 St Michael’s in late 2024 and Grade A vacancy down at 3.3%, according to Savills. Step outside the core and you are into converted Victorian textile warehouses and secondary stock in Ancoats, Openshaw and along the Oldham Road corridor, which trades on entirely different numbers and attracts a different group of lenders altogether.
What actually decides your terms
- Not the postcode. Lenders price the building and how it is used
- Let to a tenant? Assessed on the rent and the strength of that tenant
- You occupy it? Assessed on your trading profit instead
- Typical loan to value: up to 70%, occasionally 75%
- Semi-commercial: up to 75%
- Term: typically 3 to 25 years, up to 30 in rare cases
The investment versus trading distinction is the one most borrowers get caught by. The same building can fall either side of it depending on who occupies it. A let office in Spinningfields is assessed on the lease and the covenant behind it. The identical building occupied by your own firm is assessed on your trading accounts, which brings affordability, filed accounts and personal guarantees into play. Where a property has both a going concern value and a bricks and mortar value, which is normal on pubs, hotels, care homes and nurseries, the lender applies the loan to value to whichever is lower.
More than 100 lenders are active in the UK commercial mortgage market, from clearing banks and challenger banks through to building societies and non-bank specialists. Very few of them will look at every property type, and a decline from one tells you about that lender’s criteria rather than about your case. Placing it with the right one first time matters more than almost anything else, because a declined application leaves a footprint that the next lender can see.
Be realistic on timing. In our experience a commercial mortgage takes 3 to 6 months from first enquiry to completion, and longer on a complicated case. Valuation and legal work are the two stages that overrun most often. If your deadline is weeks rather than months, bridging is usually the honest answer and we will say so.
Our main commercial mortgage broker page sets out lender appetite and typical loan to value by property type, from industrial and offices through to pubs, care homes, petrol stations and places of worship.
A recent Manchester commercial mortgage
A client buying a mixed use property in north Manchester came to us in June 2025 after a high street decline. The purchase was £190,000 and they needed just under £124,000, around 65% of value. The case had two features banks tend to refuse outright, lending into retirement and an interest only exit route.
We placed it with a specialist lender rather than a bank, one that prices the borrower’s age and the exit route as part of the case instead of treating either as an automatic no. The terms agreed in 2025 were 9.49% with a 2.5% arrangement fee.
It completed and paid out on 5 December 2025, about five and a half months from first enquiry, with valuation and legal work taking most of that time.
Bridging Finance in Manchester
Bridging is the tool for speed. Manchester generates a lot of it because of the volume of conversion and refurbishment work across Ancoats, Openshaw and the eastern corridor. The usual reasons we are asked for it:
- Securing a property at auction inside the 28 day deadline
- Completing before a commercial mortgage is ready
- Taking a development site off the market while planning is resolved
- Buying a building that is unmortgageable until it is refurbished
- Exiting a development facility when units are selling slowly
Worth knowing before you rely on a quote
Lenders usually size the advance against the 180 day value rather than the open market value, so a headline 75% is often worth noticeably less cash than it looks. Ask any lender for the loan to value and the valuation basis together. On their own, neither number tells you what you will actually receive.
See bridging loans for how the advance is calculated.
Business Loans and Asset Finance in Manchester
Manchester has roughly 23,700 businesses, and about 87% of them employ fewer than ten people, on ONS UK Business Counts figures from the March 2025 snapshot. That shape matters. Most Manchester businesses are too small for a relationship bank to take much interest in, which is precisely the gap a broker fills.
- Unsecured business loan, typically 2 to 5 working days
- Asset finance, 2 to 5 working days, and credit history carries less weight because the asset is the security
- Merchant cash advance, 24 to 72 hours, suited to the city’s hospitality and retail trade
- Invoice finance, 1 to 3 weeks to set up, then same day drawdowns
Buy to Let and Property Investment in Manchester
The average Manchester house price reached £251,000 in June 2026, up 2.9% on the year, with average private rents at £1,365 a month in July 2026, on ONS and HM Land Registry figures. That relationship between price and rent is why the city draws so much landlord investment.
Business purpose only
We arrange buy to let lending on a business basis, which in practice means limited company and portfolio landlord cases. We do not arrange consumer buy to let, residential mortgages or consumer credit of any kind. If that is what you need, we will tell you and decline the enquiry rather than waste your time.
Development Finance in Manchester
Manchester has a deep pipeline of residential and mixed use schemes, from the Mayfield regeneration down to individual conversions of mill and warehouse stock. Development finance funds these in stages rather than as a lump sum:
- Day one advance against the site, released on completion of the purchase
- Build drawdowns, paid in arrears as a monitoring surveyor certifies the work completed
- Practical completion, final drawdown released and any retention settled
- Exit, loan and rolled up interest repaid from unit sales or a refinance
Expect around 65% of gross development value and up to 85% of cost, with interest rolled up and settled at exit rather than serviced monthly. The most common mistake we see is assuming the full facility lands on completion. It does not, and you need working capital to reach each certification point.
A recent Manchester development case
A Manchester developer came to us in January 2026 needing £200,000 to fund a project. We took it to four specialist lenders that April. One declined on criteria. The other three quoted between 0.89% and 0.90% per month, with arrangement fees ranging from £2,780 to £4,600.
What completed was not a development facility at all. We structured it as a second charge against other property the client already owned, rather than lending against the site itself. That removed the monitoring surveyor, the drawdown fees and the ongoing inspection costs that come with a staged development loan, and it carried an arrangement fee of £2,780 with no exit fee.
The lender was a specialist bridging lender rather than a bank, the kind that will look at how a deal is put together instead of only what it is called. Terms were signed on 26 May 2026 and the facility paid out on 30 July 2026.
Manchester Businesses We Work With
Manchester’s business base leans heavily toward professional and technical services, which account for the largest single share of employee jobs in the city at 13.2%, ahead of health and social work at 11.7% and administrative and support services at 11.5%, on ONS Business Register and Employment Survey figures. That is a very different mix from the manufacturing towns north of us, and it changes which products actually fit.
In practice the enquiries we see from Manchester cluster in a handful of places:
- Professional firms in the city core buying or refinancing the premises they trade from
- Landlords and investors buying commercial and mixed use stock in Ancoats, the Northern Quarter and out along the Oldham Road corridor
- Hospitality operators around Deansgate and the city centre funding fit outs or smoothing seasonal cash flow
- Contractors and fit out firms funding plant, vehicles and equipment
- Developers converting mill and warehouse buildings, where a bridge into a development facility is the usual structure
Manchester also formed more new companies than anywhere else in Greater Manchester during 2024, on Companies House data compiled by Inform Direct. That produces a steady flow of businesses trading perfectly well but still too young to clear mainstream lending criteria. A large part of what we do is finding the lenders who will look at them anyway.
Meeting Us in Manchester
Our office is Westgate House, Westgate Avenue, Bolton BL1 4RF. From Manchester city centre it is a straight run out on the M61, about 12 miles, 25 to 30 minutes outside rush hour and closer to 45 minutes to an hour in it. There is parking on site.
Where we will meet you
- Your own premises, anywhere across Greater Manchester
- Your accountant’s or solicitor’s office
- On site, if that is where the deal is
- Our Bolton office, with parking on site
No charge for a first meeting and no obligation to proceed.
Manchester Commercial Finance FAQs
Do you actually visit businesses in Manchester?
Yes. Manchester is about 12 miles from our Bolton office and we meet clients across the city regularly, at their premises, at their accountant’s office or on site. There is no charge for a first meeting and no obligation to proceed. If you would rather come to us, we are at Westgate House on Westgate Avenue with parking on site.
How long does a commercial mortgage take in Manchester?
In our experience 3 to 6 months from first enquiry to completion, and longer on a complicated case. Published guidance often quotes 6 to 12 weeks, which is achievable on a straightforward purchase with clean accounts and a responsive solicitor, but it is not the normal outcome. Valuation and legal work are the two stages that overrun most often.
How much can I borrow on a commercial mortgage in Manchester?
Typically up to 70% of value on commercial property, occasionally 75%, and up to 75% on semi-commercial. The figure is applied to the lower of the valuations where a property has more than one, which is normal on pubs, hotels and care homes. What you can actually service comes out of the rent if it is let, or your trading accounts if you occupy it, so the valuation is only half the answer.
Can you help if my bank has already declined me?
Often, yes. A decline tells you about that lender’s criteria rather than about whether your business can be funded. Banks can only offer their own products and will turn you away if you fall outside their boxes. We approach the lenders whose criteria your case actually fits, which frequently means a specialist or non-bank lender rather than a high street name.
Do you charge a broker fee?
On most facilities, no. We are paid a commission by the lender if you proceed, which is disclosed to you and does not increase your cost. Property secured deals are the exception and carry a £495 fee upfront plus 1% on successful completion. You will always know the position before you commit to anything.
Are you FCA regulated, and do you arrange residential mortgages in Manchester?
No to both. Bolton Business Finance Ltd is not authorised by the Financial Conduct Authority, and we do not need to be for the work we do. We arrange non-regulated commercial and business finance, lending to businesses rather than to consumers. We do not arrange residential mortgages, consumer buy to let or consumer credit of any kind.
Apply For Commercial Finance in Manchester
Tell us what you are trying to fund
Send us the details and we will come back to you, usually within 24 hours, with the options that are realistic and what they are likely to cost. If we cannot improve on what you have already been offered, we will say so.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd. He has worked in financial services since 2008, beginning his career at Santander, and has been a commercial finance broker since March 2019.
He founded Bolton Business Finance in 2020 to give businesses across Manchester, Bolton and the wider North West access to the whole lending market rather than one bank’s own product range. The firm is a member of the National Association of Commercial Finance Brokers and works with a panel of 135+ lenders.
Marcus arranges commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance and merchant cash advances. To discuss a Manchester case, call 0161 546 9128.
Bolton Business Finance Ltd is an independent commercial finance brokerage, not a lender. We are not authorised by the Financial Conduct Authority and can only complete non-regulated introductions. All lending is for business purposes only. Registered address: Westgate House, 1 Westgate Avenue, Bolton, Greater Manchester, BL1 4RF. Company number 12495909.