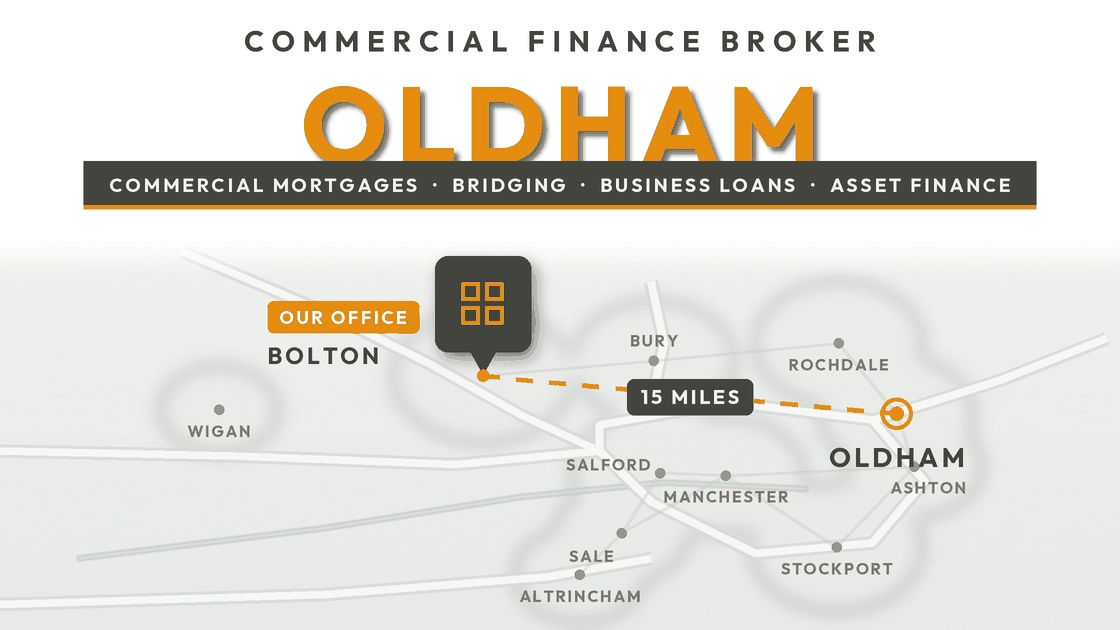
Bolton Business Finance is an independent commercial finance broker working with businesses and property investors across Oldham. We arrange commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance and merchant cash advances. Our office is fifteen miles away, about thirty minutes via the M60 and A627(M).
We are the commercial mortgage broker Oldham businesses can actually sit down with. We do not lend ourselves. We approach the lenders most likely to say yes to your particular case, and we will come to your premises rather than handle the whole thing by email.
Written by Marcus Wright, owner and founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed September 2026.
On this page
- We will come to you in Oldham
- Commercial mortgage broker Oldham
- Mills, multi-let industrial and EPC
- Business loans and asset finance
- Bridging finance in Oldham
- Buy to let and property investment
- Development finance in Oldham
- What we do not do
- Oldham businesses we work with
- Meeting us in Oldham
- Oldham commercial finance FAQs
- Apply for commercial finance in Oldham
The short version
- A commercial finance broker arranges funding for businesses from lenders across the market, rather than lending money itself.
- A commercial mortgage is a loan secured against property used for business purposes, either premises your own business trades from or a property you let to a tenant.
- UK lenders typically advance up to 70% of value on commercial property and up to 75% on semi-commercial, over terms of 3 to 25 years.
- More than 100 lenders are active in the UK commercial mortgage market. A decline from one tells you about that lender’s criteria rather than about your business.
- A commercial mortgage in Oldham usually takes 3 to 6 months from enquiry to completion. Business loans and merchant cash advances can complete in days.
We Will Come To You In Oldham
Oldham is about fifteen miles from Westgate House. The usual run is the M61 down to the M60, round to junction 22 and up the A627(M), which puts us in Oldham town centre in half an hour on a normal morning. For Saddleworth it is closer to forty minutes, and for Failsworth and Hollinwood it is a little quicker off the M60.
That matters more in Oldham than in most places, because so much of the commercial stock here needs looking at rather than reading about. A converted mill with three tenants, a yard behind a trade counter, a unit on a site with access issues. None of that comes across in a valuation summary, and lenders make very different decisions once someone has actually walked the building.
| Item | Detail |
|---|---|
| Areas covered | Oldham town centre, Chadderton, Royton, Failsworth, Hollinwood, Shaw and Crompton, Lees, and the Saddleworth villages including Uppermill, Delph, Dobcross and Greenfield |
| Distance from our office | About fifteen miles via the M61, M60 and A627(M). Thirty minutes off peak, nearer forty at rush hour or out to Saddleworth |
| Products arranged | Commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance, merchant cash advances |
| Lender panel | Over 135 lenders, from high street banks to specialist and non-bank funders |
| Broker fee | None on most facilities, we are paid a disclosed commission by the lender. Property secured deals carry £495 upfront and 1% on completion |
| First meeting | Free, at your premises, your accountant’s office or ours |
| Regulatory status | Not FCA authorised. Non-regulated business finance only. No residential mortgages |
Commercial Mortgage Broker Oldham
A commercial mortgage is a loan secured against property used for business purposes. That covers premises your own business trades from, and property you buy to let to a commercial tenant. Terms usually run 3 to 25 years, occasionally up to 30. Lenders typically advance up to 70% of value on commercial property and up to 75% on semi-commercial, meaning a shop or office with a flat above it.
Oldham is not one property market and treating it as one is how applications go wrong. Central Oldham, Hollinwood and Failsworth are dense terraced and industrial stock at the affordable end of Greater Manchester. Saddleworth, eight miles east over the moor edge, is among the most expensive property in the borough. Two commercial buildings of the same size in those two places can be worth three or four times different amounts, attract completely different lenders, and need completely different arguments made for them.
What decides your terms
- Property type. Standard industrial and offices attract the widest choice. Pubs, hotels, care homes and petrol stations attract specialists only.
- Whether you occupy it or let it. Owner occupied is assessed on your trading accounts. Investment is assessed on the rent and the strength of the tenant.
- Lease length. A short unexpired lease on an investment property narrows the field quickly.
- Trading history. Two years of filed accounts opens most doors. Less than that pushes you toward specialists.
- Condition and EPC. On older Oldham stock this decides more than people expect. See the next section.
The distinction that catches people out is investment against trading. If you are buying premises to run your own business from, the lender underwrites your business. If you are buying to let it out, the lender underwrites the rental income and the covenant behind it. Same building, two entirely different applications, and often two entirely different lists of lenders.
Be realistic on timing. In our experience a commercial mortgage takes 3 to 6 months from first enquiry to completion, and longer on a complicated case. Valuation and legal work are the two stages that overrun most often. If your deadline is weeks rather than months, bridging is usually the honest answer and we will say so.
Our main commercial mortgage broker page sets out lender appetite and typical loan to value by property type, from industrial and offices through to pubs, care homes, petrol stations and places of worship.
Mills, Multi-Let Industrial and the EPC Problem
Oldham has more surviving cotton mill floorspace than almost anywhere in England, and a large share of it is still in commercial use. Subdivided into units, let to eight or twelve small businesses, often on licences or short leases rather than proper commercial terms. If you own one or are buying one, you have probably already discovered that mainstream lenders find them difficult.
There are three reasons, and they are worth understanding before you apply anywhere.
- Tenant covenant. Twelve small tenants on rolling licences looks like risk to an underwriter, even where the income is more stable than a single tenant would be. The arithmetic favours you, the credit policy often does not.
- EPC ratings. Commercial property let in England generally needs an EPC of E or better, and the direction of travel is tighter still. Victorian mill construction rates badly almost by definition. A lender will ask what happens if the rating blocks you from re-letting, and you need an answer.
- Valuation spread. The gap between the open market value and the figure a lender will actually work to is wider on this stock than on anything else. Two valuers can land a long way apart on the same mill.
Where these cases usually land
Not with a high street bank. Multi-let industrial and mill conversions are specialist territory, and the lenders who do them well are mostly names you will not have heard of. They price a little higher, they want a proper schedule of tenancies, and they will want to see a plan for the EPC rather than a hope. Going to your own bank first and being declined costs you six weeks and puts a footprint on your file.
Business Loans and Asset Finance in Oldham
Across the UK, 99.18% of businesses employ fewer than 50 people and around three quarters employ nobody beyond the owners, according to the government’s Business Population Estimates for 2025. Oldham’s business base sits firmly at that end. That matters because most high street lending policy is built around businesses considerably larger, which is why small firms with perfectly sound trading get turned away.
What we arrange most often for Oldham businesses:
- Unsecured business loans, typically £10,000 to £500,000, decisions in days rather than weeks
- Secured business loans, larger sums against property, slower but cheaper
- Asset finance, for vehicles, plant and machinery, with nil deposit options and no broker fee
- Invoice finance, releasing cash tied up in unpaid invoices, which suits engineering, haulage and contracting
- Merchant cash advances, repaid as a percentage of card takings, which suits retail and hospitality
If you have already been declined
A decline tells you about that lender’s criteria rather than about whether your business can be funded. Lenders refuse cases for reasons that have nothing to do with the strength of the business: sales below their minimum, a director who does not own a home, a payment provider their systems cannot read, an application already sitting with another introducer. We have placed cases that had been turned down repeatedly, with nothing about the business having changed. What changed was which lender was looking at it.
Bridging Finance in Oldham
Bridging is short term property lending, usually three to eighteen months, priced monthly and repaid from a sale or a refinance. In Oldham it comes up most often on stock that no term lender will touch in its current state, which given the age of the building stock here is a great deal of it.
- Buying at auction, where completion is fixed at twenty eight days
- Buying a property no mainstream lender will touch, typically no kitchen, no bathroom or serious damp
- Buying a mill or industrial building that needs work before it can be let or refinanced
- Breaking a chain when a sale slips
- Raising working capital quickly against property already owned
The number that catches people out
Bridging lenders size the loan against the 180 day value, not the open market value. That is what the property would fetch in a forced six month sale, and it is routinely 10% to 20% below the figure in the valuation you paid for. On unusual Oldham stock, mills and mixed industrial in particular, the gap can be wider still. If you have budgeted on the headline valuation, the advance can land well short of what you planned for.
Buy To Let and Property Investment in Oldham
Oldham is doing something interesting on the numbers, and it is close to the opposite of what neighbouring Bury is doing. According to ONS and HM Land Registry data published in August 2026, the average house price in Oldham was £215,000 in June 2026, up 5.1% on the year. Average private rent was £931 a month in July 2026.
The figure worth pausing on is the rent growth. Oldham rents rose 11.0% over the year to July 2026. Across the North West they rose 5.7%. Oldham rents grew at close to double the regional rate, from a lower base, while prices also outpaced the region.
On the headline averages that puts gross yield around 5.2%, roughly in line with the North West, but moving in the right direction rather than compressing. Oldham property also remains cheaper than the regional average of £220,000, which means a given deposit buys more units here than in most of Greater Manchester. That combination is why a large share of the investor cases we see in the borough are portfolio purchases rather than single properties.
What lenders will do about it is a separate question. Rent rising 11% in a year is recent, and a lender stressing affordability will test the rent against the payment at a rate well above what you are actually paying. Fast recent growth does not soften that test. If anything it makes valuers more cautious, because they are pricing a market that has moved quickly.
Business purpose only
We arrange buy to let and property investment finance on a business basis only, through limited companies, partnerships and portfolio landlords. We do not arrange consumer buy to let, which covers property you have lived in or inherited, or that a close family member occupies. Those cases are regulated and we cannot help with them.
Development Finance in Oldham
Development finance funds a build rather than a purchase. It is released in stages against certified progress, with interest rolled up and settled at exit rather than serviced monthly. In Oldham it most often funds small residential schemes, mill and industrial conversions, and infill sites in the older parts of the borough.
- Day one advance against the site, released on completion of the purchase
- Build drawdowns, paid in arrears as a monitoring surveyor certifies the work completed
- Practical completion, final drawdown released and any retention settled
- Exit, loan and rolled up interest repaid from unit sales or a refinance
Expect around 65% of gross development value and up to 85% of cost. The most common mistake we see is assuming the full facility lands on completion. It does not, and you need working capital to reach each certification point. On smaller schemes it is sometimes cheaper to structure the money a different way entirely, as a charge against other property you already own, which removes the monitoring surveyor, the drawdown fees and the ongoing inspection costs.
What We Do Not Do
A fair number of people reach this page looking for a residential mortgage broker in Oldham. We are not one, and we would rather say so plainly than waste your time.
We cannot help with these
- Residential mortgages, including first time buyer, home mover and remortgage
- Consumer buy to let, meaning property you have lived in, inherited, or that a close family member occupies
- Self employed residential mortgages
- Any form of consumer credit or personal borrowing
Bolton Business Finance Ltd is not authorised by the Financial Conduct Authority. Those products are regulated and require FCA authorisation, so arranging them would be outside what we are permitted to do. For a residential mortgage you need an FCA authorised mortgage broker, and any local independent adviser in Oldham will be able to help.
What we do arrange is lending to businesses. Limited companies, partnerships, sole traders trading commercially and property investors buying on a business basis. If you are buying premises, funding stock, replacing a van, smoothing cash flow or building something out, that is our side of the line.
Oldham Businesses We Work With
Oldham’s economy divides along geography more sharply than most boroughs, and each part of it tends to need a different product.
- Chadderton and Broadway manufacturing and distribution. The employment spine of the borough, sitting on the M60. Asset finance for plant and vehicles, invoice finance where they supply on credit terms, and commercial mortgages where they own the unit.
- Hollinwood and Failsworth trade and logistics. Trade counters, builders merchants, small hauliers and the businesses that serve the M60 corridor. Usually asset finance and working capital.
- Mill landlords and multi-let industrial owners. Spread across the older parts of the borough. Commercial mortgages and bridging, almost always with a specialist lender rather than a bank.
- Saddleworth independents. Restaurants, pubs, delis, shops and holiday lets across Uppermill, Delph, Dobcross and Greenfield. Seasonal trading that lenders find hard to underwrite from a single set of accounts, so often merchant cash advance or a short term facility.
- Construction and trades across Royton, Shaw and Lees. Groundworks, electrical, joinery and building contractors. Usually invoice finance or asset finance, because the money is tied up in applications and retentions.
Meeting Us in Oldham
We are at Westgate House on Westgate Avenue in Bolton, BL1 4RF, with parking on site. From Oldham the quickest route is the A627(M) down to the M60 and round to the M61, which is about half an hour outside peak times. If you are coming from Saddleworth allow longer, and if you would rather not make the trip at all we will come to you.
Where we will meet you
- At your premises, anywhere in the borough including Chadderton, Royton, Shaw, Failsworth, Lees and the Saddleworth villages
- At your accountant’s or solicitor’s office, which is often the most useful option on a property purchase
- On site, which on mill and industrial cases is usually the only way to understand the building properly
- At our office in Bolton, half an hour away, with parking
Oldham Commercial Finance FAQs
Do you actually visit businesses in Oldham?
Yes. Oldham is about fifteen miles from our Bolton office, roughly half an hour via the M60 and A627(M), and we cover the whole borough including Saddleworth. We meet clients at their premises, at their accountant’s office or on site. There is no charge for a first meeting and no obligation to proceed. If you would rather come to us, we are at Westgate House on Westgate Avenue with parking.
Can you finance a mill or a multi-let industrial building in Oldham?
Yes, though rarely with a high street bank. Multi-let industrial and converted mills are specialist territory because of tenant covenant, EPC ratings and a wide valuation spread. The lenders who do this well are mostly non-bank names, they price a little above mainstream, and they will want a full schedule of tenancies and a credible plan for the EPC rather than an intention. Going to your own bank first usually costs six weeks and leaves a footprint on your file.
Do you arrange residential mortgages in Oldham?
No. Bolton Business Finance Ltd is not authorised by the Financial Conduct Authority, and residential mortgages are a regulated product that requires authorisation. We do not arrange residential mortgages, consumer buy to let, self employed residential mortgages or any form of consumer credit. We arrange business finance only. For a residential mortgage you need an FCA authorised mortgage broker.
How long does a commercial mortgage take in Oldham?
In our experience 3 to 6 months from first enquiry to completion, and longer on a complicated case. Published guidance often quotes 6 to 12 weeks, which is achievable on a straightforward purchase with clean accounts and a responsive solicitor, but it is not the normal outcome. Valuation and legal work are the two stages that overrun most often, and on unusual Oldham stock the valuation stage runs longer than average.
How much can I borrow on a commercial mortgage in Oldham?
Typically up to 70% of value on commercial property, occasionally 75%, and up to 75% on semi-commercial. Where a property has more than one valuation, which is normal on pubs, hotels and care homes, the figure is applied to the lower one. What you can actually service comes out of the rent if it is let, or your trading accounts if you occupy it, so the valuation is only half the answer.
Do you charge a broker fee?
On most facilities, no. We are paid a commission by the lender if you proceed, which is disclosed to you and does not increase your cost. Property secured deals are the exception and carry a £495 fee upfront plus 1% on successful completion. You will always know the position before you commit to anything.
Apply For Commercial Finance in Oldham
Tell us what you are trying to fund
Send us the details and we will come back to you, usually within 24 hours, with the options that are realistic and what they are likely to cost. If we cannot improve on what you have already been offered, we will say so.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd. He has worked in financial services since 2008, beginning his career at Santander, and has been a commercial finance broker since March 2019.
He founded Bolton Business Finance in 2020 to give businesses access to the whole lending market rather than one bank’s own product range. The firm is a member of the National Association of Commercial Finance Brokers and works with a panel of 135+ lenders.
Marcus arranges commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance and merchant cash advances. To discuss an Oldham case, call 0161 546 9128.
Marcus is also the author of UK Commercial Finance (2026), a commercial finance book for UK business owners and property investors.
Bolton Business Finance Ltd is an independent commercial finance brokerage, not a lender. We are not authorised by the Financial Conduct Authority and can only complete non-regulated introductions. All lending is for business purposes only. We do not arrange residential mortgages, consumer buy to let or consumer credit. Registered address: Westgate House, 1 Westgate Avenue, Bolton, Greater Manchester, BL1 4RF. Company number 12495909.