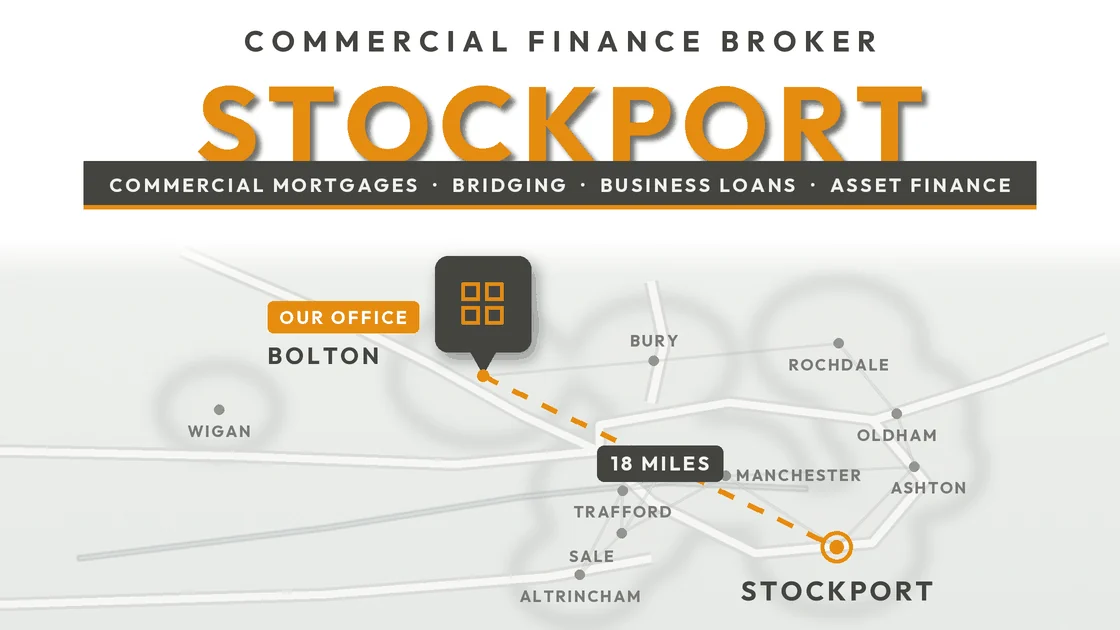
Bolton Business Finance is an independent commercial finance broker working with businesses and property investors across Stockport. We arrange limited company buy to let and property investment finance, commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance and merchant cash advances. Stockport is about eighteen miles from our office, roughly thirty five minutes on the M61 and M60.
We arrange buy to let and commercial mortgages in Stockport for limited company landlords, portfolio investors and businesses buying their own premises. We do not lend ourselves. We approach the lenders most likely to say yes to your particular case. In Stockport that work starts earlier than most people expect, because this is an expensive borough with thin rental yields, and the amount you can borrow here is usually decided by the rent rather than by the deposit you have available.
Written by Marcus Wright, owner and founder of Bolton Business Finance Ltd, in financial services since 2008 and a commercial finance broker since 2019. Last reviewed September 2026.
On this page
- We will come to you in Stockport
- Buy to let and property investment in Stockport
- Why the rent, not the deposit, sets your loan size here
- Commercial mortgage broker Stockport
- Bridging and development finance
- Business loans and asset finance
- What we do not do
- Stockport businesses we work with
- Meeting us in Stockport
- Stockport commercial finance FAQs
- Apply for commercial finance in Stockport
The short version
- A commercial finance broker arranges funding for businesses from lenders across the market, rather than lending money itself.
- Buy to let finance arranged through a limited company is business lending. Buy to let on a property you or a family member will live in is regulated and we cannot arrange it.
- Stockport had the second highest average house price in the North West in June 2026, and the gross rental yield here is the thinnest of anywhere we cover.
- That matters practically: on an average priced Stockport property the rent supports a loan of roughly 62% of value, not the 75% most investors assume.
- UK lenders typically advance up to 70% of value on commercial property and up to 75% on semi-commercial, over terms of 3 to 25 years.
We Will Come To You In Stockport
Stockport is about eighteen miles from Westgate House, normally thirty five minutes out on the M61 and round the M60. Reddish and the Heatons are a little closer. Marple, Romiley and Hazel Grove are further out on the eastern edge and worth allowing a bit longer for.
On Stockport buy to let in particular, a conversation before you offer is worth more than one afterwards. The borrowing limit here is set by the rent, and working out what a given property will actually support takes about ten minutes. Finding out after your offer has been accepted that you need another forty thousand in deposit is a considerably worse way to learn it.
| Item | Detail |
|---|---|
| Areas covered | Stockport town centre, the Underbanks and Old Town, Edgeley, Heaton Moor, Heaton Chapel, Heaton Norris, Reddish, Cheadle, Cheadle Hulme, Gatley, Bramhall, Hazel Grove, Marple, Romiley, Bredbury, Woodley and Offerton |
| Distance from our office | About eighteen miles, roughly thirty five minutes on the M61 and M60 |
| Products arranged | Limited company buy to let, commercial mortgages, bridging, development finance, business loans, asset finance, invoice finance, merchant cash advances |
| Lender panel | Over 135 lenders, from high street banks to specialist and non-bank funders |
| Broker fee | None on most facilities, we are paid a disclosed commission by the lender. Property secured deals carry £495 upfront and 1% on completion |
| First meeting | Free, at your premises, your accountant’s office or ours |
| Regulatory status | Not FCA authorised. Non-regulated business finance only. No residential mortgages and no consumer buy to let |
Buy To Let and Property Investment in Stockport

According to ONS and HM Land Registry data, the average house price in Stockport was £314,000 in June 2026, up 3.5% on the year. ONS notes that this gave Stockport the second highest average house price in the North West, where the regional average was £220,000. Average private rent was £1,111 a month in July 2026, up 5.1% from £1,057.
Put those together and the gross yield is about 4.2%, effectively unchanged on last year. That is the thinnest yield of any area we cover, and it is thin for a straightforward reason: Stockport is expensive to buy in without being proportionately expensive to rent in.
The borough average hides an unusually wide spread
Stockport contains Bramhall, Cheadle Hulme, Marple and Heaton Moor, and it also contains areas that sit a very long way from those in value terms. An average of £314,000 across all of it is a weaker guide to any particular street than the equivalent figure is in a smaller, more uniform town. Treat it as context for the direction of travel rather than as a valuation, and if you want a realistic read on a specific address, that is a job for local comparables rather than a borough number.
| Property type | Average price, June 2026 | Average rent, July 2026 | Gross yield |
|---|---|---|---|
| Flats and maisonettes | £174,000 | £947 | 6.5% |
| Terraced | £251,000 | £1,111 | 5.3% |
| Semi-detached | £344,000 | £1,215 | 4.2% |
| Detached | £549,000 | £1,549 | 3.4% |
The spread down that column is the point. Flats show 6.5% and detached houses 3.4%, and a detached house at 3.4% gross will struggle to satisfy a lender’s rental cover test at any sensible loan to value. That does not make it a bad purchase, but it does mean it is close to a cash or low leverage proposition rather than a geared one, and it is better to know that before you start than after a declined application.
Business purpose only
We arrange buy to let and property investment finance on a business basis only, through limited companies, partnerships and portfolio landlords. We are not FCA authorised and we do not arrange consumer buy to let, regulated buy to let or any residential mortgage. If the property is or will be lived in by you or a close family member, that is regulated business and you need an FCA authorised mortgage adviser instead.
Why The Rent, Not The Deposit, Sets Your Loan Size In Stockport
This is the part of a Stockport purchase that catches experienced investors out, including ones who have bought successfully elsewhere in Greater Manchester for years.
Buy to let lending is not sized by your income. It is sized by whether the rent covers the mortgage interest by a set margin, tested at a stress rate rather than the rate you will actually pay. The margin is commonly 125% for a limited company borrower. So the lender is asking a simple question: does this property’s rent cover the stressed interest with a quarter to spare?
In most of the areas we cover the answer is yes at 75% loan to value, and the deposit is what limits you. In Stockport the answer is frequently no, and the rent is what limits you. Here is the same calculation run across three places in our patch, on identical assumptions.
| Area | Average price | Average rent | Loan the rent supports | As % of value | What limits the loan |
|---|---|---|---|---|---|
| Stockport | £314,000 | £1,111 | About £194,000 | About 62% | The rent |
| Rochdale | £210,000 | £844 | About £147,000 | About 70% | The rent |
| Blackpool | £135,000 | £714 | About £125,000 | About 92% | The 75% cap |
In Blackpool the rent would comfortably support more than the lender will lend, so the loan to value cap bites first and you simply put down 25%. In Stockport the rent runs out well before the cap does. On an average priced property that is the difference between a deposit of about £78,500 and a deposit of about £120,000, so roughly £41,500 more cash for the same purchase.
Read the assumptions before you use these numbers
The figures above use 125% interest cover and a 5.5% stress rate, applied consistently so the three areas can be compared. Both vary in practice. Cover ratios differ between limited company and personal ownership and between basic and higher rate taxpayers. Stress rates differ by lender, by product and by the length of the fixed period, and some lenders apply a floor rate regardless of the rate you are paying. Treat this as an illustration of the mechanism, not as a quote. What does not vary is the mechanism itself, and in Stockport the mechanism is the binding constraint.
There is a practical consequence worth knowing. Lenders generally stress five year fixed products more gently than two year ones, because the borrower is protected from rate movement for longer. In a low yield area that difference is not a minor preference, it is often the whole reason a case works. Investors in Stockport frequently end up on a five year fix not because they wanted to fix for five years but because it is the only structure that produces the loan size they need. If your plan involves refinancing in two years, say so early, because it narrows the options considerably here in a way it would not in Blackpool or Burnley.
- Get a realistic rental figure first. Not the agent’s optimistic one. The whole calculation hangs off it.
- Work out what that rent supports at the cover ratio and stress rate the lender will actually use.
- Compare that to your deposit. Whichever is smaller is your real borrowing limit.
- Then choose the product, knowing that the fixed period affects the loan size and not just the rate.
Commercial Mortgage Broker Stockport
A commercial mortgage is a loan secured against property used for business purposes. That covers premises your own business trades from, and property you buy to let to a commercial tenant. Terms usually run 3 to 25 years, occasionally up to 30. Lenders typically advance up to 70% of value on commercial property and up to 75% on semi-commercial, meaning a shop or office with a flat above it.
Stockport town centre is in the middle of a long transition, around the Underbanks and Old Town, the Interchange, Weir Mill and the office development at Stockport Exchange. That creates genuine opportunity in older commercial and mill stock, and it creates one specific funding problem that is worth understanding before you commit.
Valuations lag a changing area
A valuer’s job is to evidence a figure, and the evidence available is what has already sold nearby. In a stable market that works well. In an area that is actively changing, recent comparables describe what the street used to be worth rather than what it is becoming worth. So a buyer paying a forward looking price meets a backward looking valuation, and the gap lands on the buyer as extra deposit.
This is not a reason to avoid Stockport town centre. It is a reason to build the possibility into your numbers, to be wary of pricing based on what the agent says the area will be like in three years, and to expect that the more genuinely transitional the building is, the wider the range of valuations you could reasonably receive on it.
What decides your terms
- Property type. Standard industrial, warehousing and offices attract the widest choice. Pubs, hotels, care homes and petrol stations attract specialists only.
- Whether you occupy it or let it. Owner occupied is assessed on your trading accounts. Investment is assessed on the rent and the strength of the tenant.
- Lease length. A short unexpired lease on an investment property narrows the field quickly.
- Trading history. Two years of filed accounts opens most doors. Less than that pushes you toward specialists.
- Condition and EPC. Commercial property let in England generally needs an EPC of E or better, and older town centre stock is where that most often bites.
- Change of use. If the plan depends on a consent you do not yet hold, most lenders will treat it as a development case rather than a straight commercial mortgage.
Be realistic on timing. In our experience a commercial mortgage takes 3 to 6 months from first enquiry to completion, and longer on a complicated case. Valuation and legal work are the two stages that overrun most often. If your deadline is weeks rather than months, bridging is usually the honest answer and we will say so.
Our main commercial mortgage broker page sets out lender appetite and typical loan to value by property type, from industrial and offices through to pubs, care homes, petrol stations and places of worship.
Bridging and Development Finance in Stockport
Bridging is short term property lending, usually three to eighteen months, priced monthly and repaid from a sale or a refinance. In Stockport it comes up on auction purchases, on older town centre and Underbanks stock bought below mortgageable condition, and on conversion work where the end use is not the current use.
- Buying at auction, where completion is fixed at twenty eight days
- Buying a property no mainstream lender will touch, typically no kitchen, no bathroom or serious damp
- Refurbishing before refinancing onto a term buy to let facility
- Breaking a chain when a sale slips
- Raising working capital quickly against property already owned
The number that catches people out
Bridging lenders size the loan against the 180 day value, not the open market value. That is what the property would fetch in a forced six month sale, and it is routinely 10% to 20% below the figure in the valuation you paid for. On higher value Stockport stock that percentage translates into a large absolute sum, so run your numbers off the cautious figure from the outset rather than the headline one.
There is a second point specific to Stockport, and it follows directly from the yield problem above. Bridging is repaid from a sale or a refinance, and if your exit is a refinance onto a buy to let facility, that facility is subject to the same rental cover test. A bridge with a refinance exit that the rent will not actually support is a bridge without an exit. Work the term loan out first and the bridge second, not the other way round.
Development finance funds building work rather than a purchase, released in stages against a schedule of works with a valuer signing off each drawdown.
- Land or acquisition drawdown. Usually up to 60% to 70% of the purchase price, released on completion.
- Staged build drawdowns. Released in arrears against work completed and signed off by the lender’s monitoring surveyor.
- Practical completion. Final drawdown, and the point at which the exit route has to be real rather than intended.
- Exit. Sale of the units, or refinance onto a commercial mortgage or buy to let facility.
Business Loans and Asset Finance in Stockport
Across the UK, 99.18% of businesses employ fewer than 50 people and around three quarters employ nobody beyond the owners, according to the government’s Business Population Estimates for 2025. Stockport’s business base leans toward professional services, engineering and the sort of established owner managed firms that have been in the borough a long time, and the great majority sit at that small end.
What we arrange most often for Stockport businesses:
- Unsecured business loans, typically £10,000 to £500,000, decisions in days rather than weeks
- Asset finance, for vehicles, plant and production equipment, with nil deposit options and no broker fee
- Invoice finance, releasing cash tied up in unpaid invoices, which suits engineering, professional services and contractors working on payment terms
- Secured business loans, larger sums against property, slower but cheaper
- Merchant cash advances, repaid as a percentage of card takings, which suits retail and hospitality
If you have already been declined
A decline tells you about that lender’s criteria rather than about whether your business can be funded. Lenders refuse cases for reasons that have nothing to do with the strength of the business: sales below their minimum, a director who does not own a home, a payment provider their systems cannot read, an application already sitting with another introducer. We have placed cases that had been turned down repeatedly, with nothing about the business having changed. What changed was which lender was looking at it.
What We Do Not Do
We do not arrange residential mortgages, and we do not arrange consumer buy to let. Some people reach this page looking for a mortgage broker in Stockport for a home to live in, or for a first buy to let in their own name. We cannot help with either.
Business buy to let, held through a limited company or as part of a genuine property investment business, is not regulated and we can arrange it. Consumer buy to let, broadly where you did not set out to be a landlord, or where the property has been or will be lived in by you or a close family member, is regulated and we cannot.
Bolton Business Finance Ltd is not authorised or regulated by the Financial Conduct Authority. We arrange non-regulated commercial and business finance only. That means we cannot advise on or arrange: residential mortgages, first time buyer mortgages, remortgages of your own home, consumer buy to let, equity release, or any consumer credit.
If you need any of those, use the FCA’s Financial Services Register to find an authorised adviser. If you are a business owner, a landlord holding property through a company, or a property investor funding on a commercial basis, then you are in the right place.
Stockport Businesses We Work With
- Property investors and portfolio landlords, across the Heatons, Reddish, Edgeley and the town centre. Limited company buy to let, portfolio refinancing and bridging, with the rental cover question front and centre on nearly every case.
- Professional services firms, around the town centre and Stockport Exchange. Working capital, office purchase and partner buy-ins.
- Engineering and manufacturing businesses, across Bredbury, Reddish and the industrial estates. Asset finance for plant and machinery, and owner occupier commercial mortgages.
- Independent retail and hospitality, in the Old Town and Underbanks, in Marple and across the suburban centres. Merchant cash advances, fit-out finance and short term working capital.
- Construction and trades, where the problem is nearly always the gap between doing the work and being paid for it.
Meeting Us in Stockport
We do not have an office in Stockport and we are not going to pretend otherwise. We are based at Westgate House in Bolton, about eighteen miles and thirty five minutes away, and we travel to Stockport regularly.
Where we will meet you
- At the property, which on town centre and Underbanks stock is worth doing, because condition and access drive both the valuation and the lender shortlist.
- At your premises or office, anywhere from Reddish and the Heatons through to Cheadle, Bramhall, Hazel Grove and Marple.
- At your accountant’s office, which often saves a meeting later when the figures come up.
- At ours in Bolton, if you would rather come to us. Free parking.
Stockport Commercial Finance FAQs
Do you actually visit clients in Stockport?
Yes. Stockport is about eighteen miles from our Bolton office, roughly thirty five minutes on the M61 and M60. We cover the town centre and Old Town, Edgeley, the Heatons, Reddish, Cheadle, Cheadle Hulme, Gatley, Bramhall, Hazel Grove, Marple, Romiley, Bredbury, Woodley and Offerton. We meet clients at their premises, at the property, or at their accountant’s office. There is no charge for a first meeting and no obligation to proceed. If you would rather come to us, we are at Westgate House, Westgate Avenue, Bolton, BL1 4RF.
Why can I not borrow 75% on a Stockport buy to let?
Because in Stockport the rent usually runs out before the loan to value cap does. Buy to let lending is sized by whether the rent covers the mortgage interest by a set margin at a stress rate, commonly 125% cover for a limited company borrower. Stockport has the second highest average house price in the North West but not proportionately high rents, so the gross yield is around 4.2%, the thinnest of anywhere we cover. On an average priced property at 125% cover and a 5.5% stress rate, the rent supports a loan of roughly £194,000 against a £314,000 value, which is about 62% rather than 75%. Cover ratios and stress rates vary by lender and product, so treat that as an illustration of the mechanism rather than a quote. One practical point: five year fixed products are generally stressed more gently than two year ones, so in a low yield area the length of the fix often decides the loan size, not just the rate.
How long does a commercial mortgage take?
Typically 3 to 6 months from first enquiry to completion, and longer on a complicated case. Valuation and legal work are the two stages that overrun most often. If your deadline is weeks rather than months, bridging is usually the honest answer and we will tell you that rather than start an application that cannot land in time.
How much can I borrow?
On commercial property, typically up to 70% of value, or up to 75% on semi-commercial. On limited company buy to let it is driven by the rental income against the stressed payment rather than by your own income, and in Stockport that test is usually what limits the loan. On unsecured business loans, commonly £10,000 to £500,000 depending on turnover and trading history. On asset finance it is driven by the asset itself, with nil deposit options available.
Can you help if I have already been declined?
Often, yes. A decline reflects one lender’s criteria, not a verdict on your business. Lenders turn cases down for reasons that have nothing to do with whether the business is sound, and with more than 135 lenders on our panel the question is usually which one to approach rather than whether anyone will look at it. Tell us who has already seen the case, because approaching the same lender twice through a different route does not help you.
Do you charge a broker fee?
Not on most facilities. On business loans, asset finance, invoice finance and merchant cash advances we are paid a commission by the lender, which is disclosed to you. Property secured deals carry a £495 upfront fee and 1% on completion. You will know the full cost before anything is submitted.
Apply For Commercial Finance in Stockport
Tell us what you need funding for
Send us the outline and we will tell you honestly whether it is fundable, roughly what it should cost, and how long it will take. On a Stockport buy to let, send the asking price and the expected rent and we will tell you what the rent actually supports before you offer. No charge for the conversation and no obligation to proceed. Call 0161 546 9128 or use the form below.
About the author
Marcus Wright is the owner and founder of Bolton Business Finance Ltd. He has worked in financial services since 2008, beginning at Santander, and has been a commercial finance broker since March 2019. He founded the firm in 2020 and is a member of the National Association of Commercial Finance Brokers.
He arranges commercial mortgages, bridging finance, development finance, business loans, asset finance, invoice finance and merchant cash advances for UK businesses, working with a panel of more than 135 lenders. He can be reached on 0161 546 9128.
Marcus is also the author of UK Commercial Finance (2026), a commercial finance book for UK business owners and property investors.
Bolton Business Finance Ltd is registered in England and Wales, company number 12495909. Registered office: Westgate House, Westgate Avenue, Bolton, BL1 4RF.
Bolton Business Finance Ltd is not authorised or regulated by the Financial Conduct Authority. We arrange non-regulated commercial and business finance only, and do not advise on or arrange residential mortgages, consumer buy to let, equity release or consumer credit. All finance is subject to status, lender criteria and credit assessment. Your property may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.